3-Year-OldShelf Company
An entry-level option for entrepreneurs seeking an existing legal entity with a relatively recent formation history.
3 YearsOld
LLC or CorpOptions
GoodStanding
$1,700Package price
Request DetailsEstablished Companies. Verifiable Records. Compliant, Ready for Business.
Step-by-Step Credit Roadmap
Learn how to establish, build and strengthen business credit from the ground up—fundability, credit bureaus, reporting accounts, credit tiers, and how an aged Colorado company may help with time-in-business requirements.
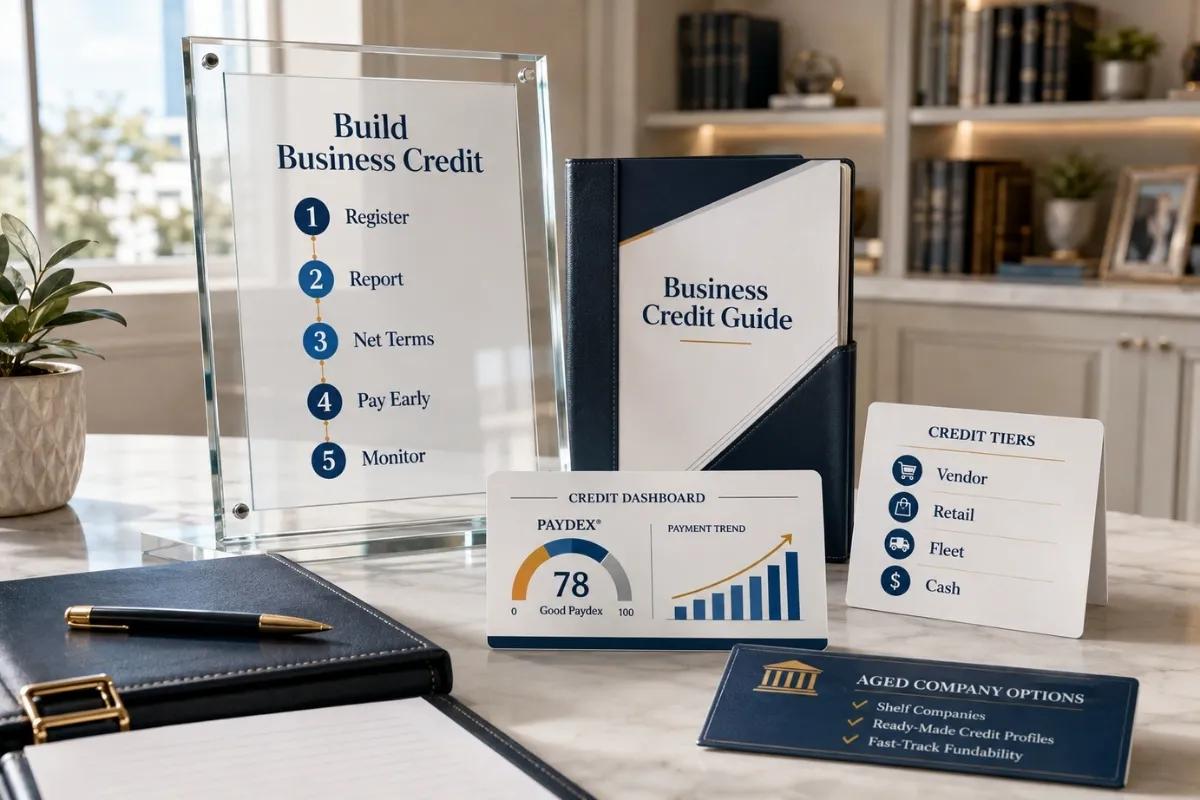
The Fundamentals
Business credit is a financial profile attached to your company, separate from your personal credit score. Lenders, vendors and suppliers use it to evaluate reliability and payment history.
Dun & Bradstreet, Experian Business and Equifax Business each keep independent files. Lenders generally look for the “3 Cs”—Credit, Collateral or Cash Flow. A business with few reporting accounts is often treated as unestablished.
Your company can develop a credit file that is distinct from your personal credit history.
Business accounts may offer larger limits than consumer accounts, subject to each lender's review.
A mature profile may support some financing with fewer personal guarantees—though many lenders still require one.
Suppliers often prefer companies with an established, on-time payment record.
A stronger profile can support better rates and terms over time.
From commercial leases to contract bids, a consistent record signals stability.
It depends on how actively and consistently you build.
30–60 days
Baseline profile: first reporting vendor accounts appear.
3–6 months
Functional profile with multiple reporting tradelines.
6–18 months
Possible access to bank cards and lines of credit.
18+ months
A well-rounded, lender-ready profile for many applicants.
General ranges based on consistent account management—not guarantees.
Plan First
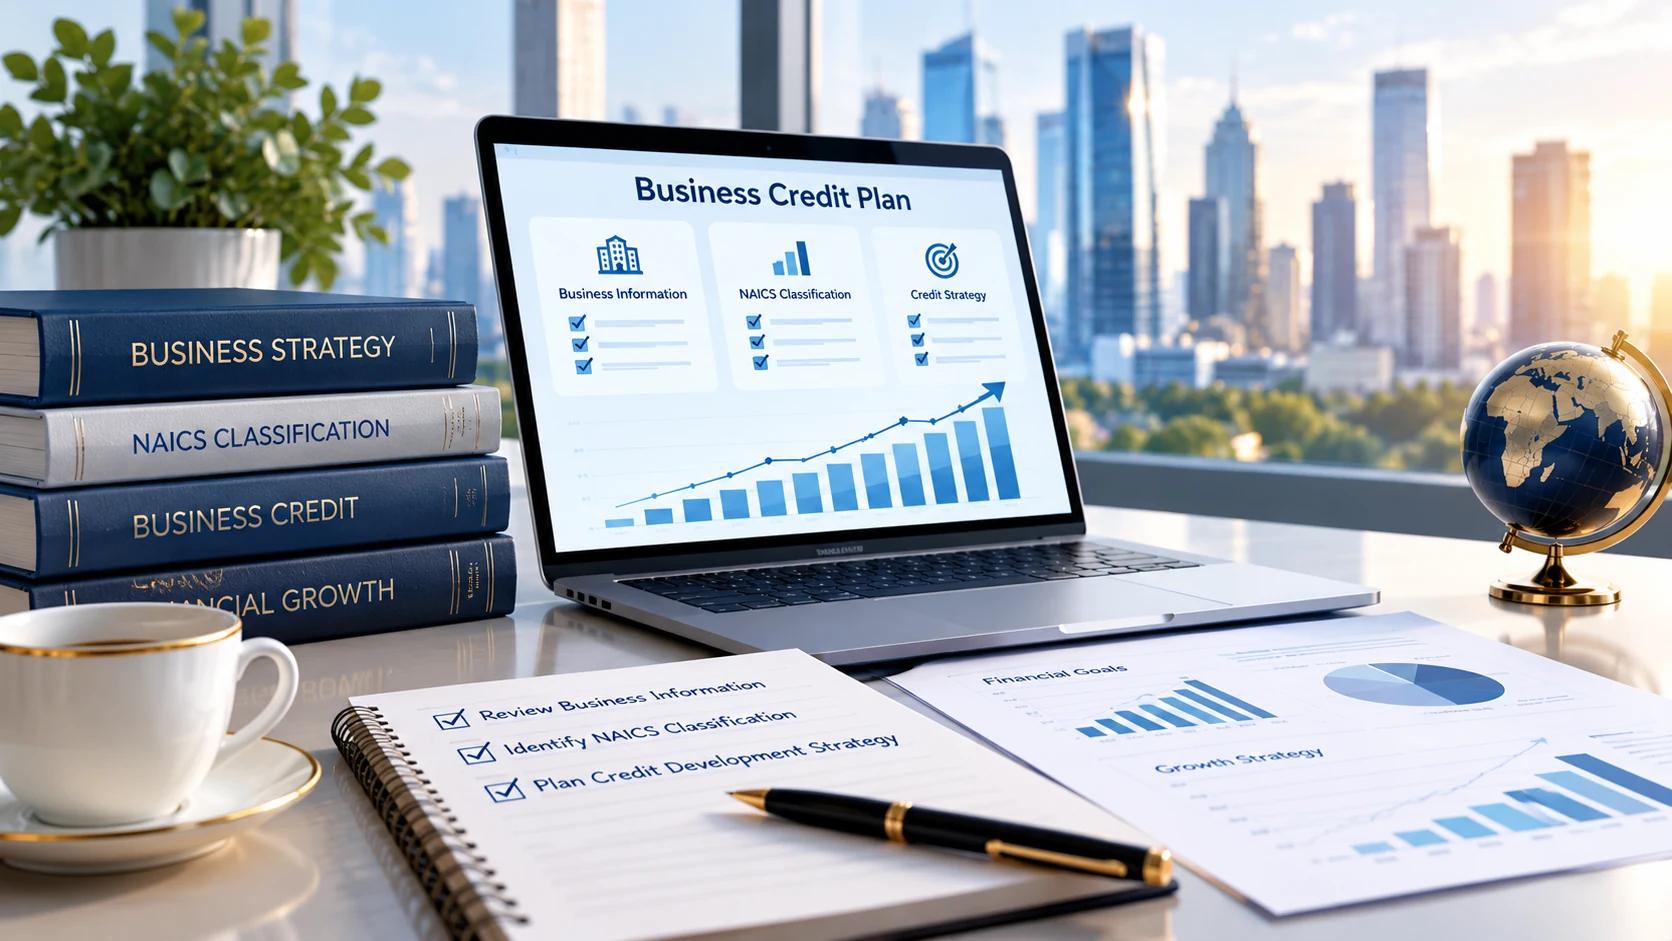
Start with a strategy tailored to your industry, goals and current profile. Before applying, review your business information, confirm the right NAICS classification and understand each step below.
Try the Credit Readiness AssistantThe Process
Build a company record that reads as legitimate and consistent everywhere it is checked.
Open your files with each bureau, then keep them accurate.
Most vendors don't report payment history. Ask each supplier what it reports before you apply—policies change.
| Vendor | Commonly reports to |
|---|---|
| Uline | Dun & Bradstreet |
| Quill | Dun & Bradstreet |
| Grainger | Multiple bureaus |
| Summa Office Supplies | D&B, Equifax |
| Reliable Office Supplies | D&B, Experian, Equifax |
| Supply Works | Experian |
Let each tier report before applying for the next. Many simultaneous applications can signal risk rather than strength.
Tier 1 — Vendor credit
Typically needs: Starting point · May unlock: Net-terms starter accounts
Tier 2 — Retail credit
Typically needs: Several reporting accounts · May unlock: Store and retail business cards
Tier 3 — Fleet credit
Typically needs: A broader payment history · May unlock: Fuel and fleet cards
Tier 4 — Bank credit
Typically needs: An established profile · May unlock: Bank cards and credit lines
Protect Personal Credit
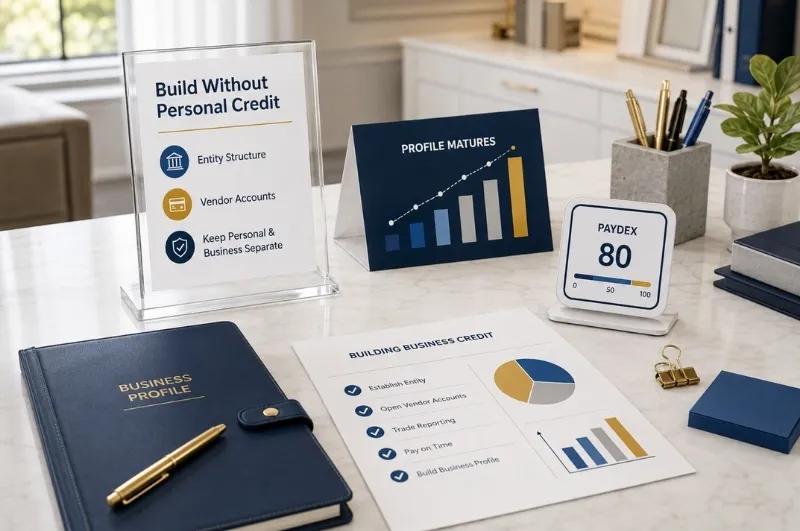
Scores
1–100
Based on business payment history and dollar-weighted, so larger invoices carry more influence.
1–100
Considers payment history, utilization, company age and public records; higher is lower risk.
101–992
Higher is lower risk; it often builds more slowly than other files.
0–300
Blends personal and business data; the SBA uses it to prescreen smaller 7(a) loans.
| PAYDEX score | Risk level |
|---|---|
| 80–100 | Low risk — pays on time or early |
| 50–79 | Moderate risk — some late payments |
| 1–49 | High risk — consistently late |
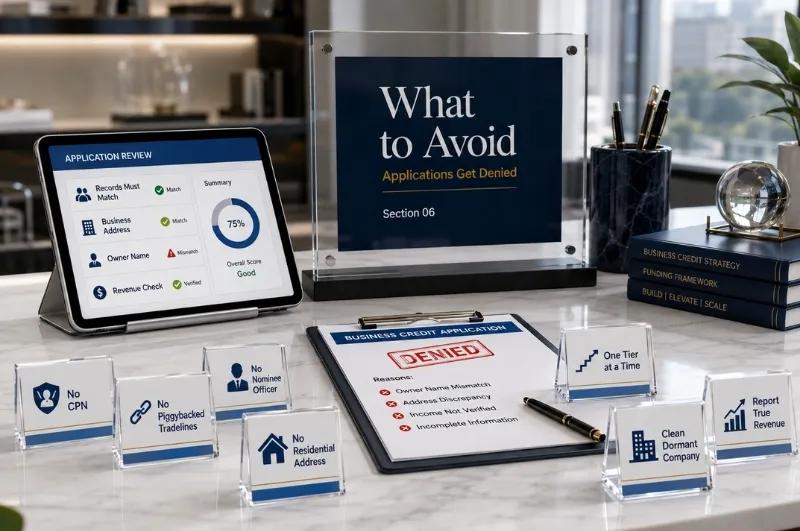
Avoid Denials
LexisNexis Risk Solutions: Cross-references addresses, phone and email history and public records.
Small Business Financial Exchange (SBFE): Aggregates payment and credit data from member lenders.
ChexSystems: Tracks banking history that can affect opening a bank account.
Every record—state filing, IRS, bureaus, bank and vendor applications—should match exactly, down to spelling and address format.
Time-in-Business
A shelf company is a legally formed entity maintained without activity for a period of years. Many lenders and vendors set minimum time-in-business requirements, and an aged entity may help address that screen.
Read before purchasing: an earlier formation date is not operating history or a credit score. Payment history still has to be built after you take ownership, and approval is never guaranteed.
Compare States
Ongoing state costs differ. Colorado combines a low annual periodic report fee with publicly searchable Secretary of State records. The figures below are the standard LLC charge; corporation costs can be higher, and are listed separately on the homepage comparison.
| State | Annual report fee (LLC) |
|---|---|
| Colorado | $25/yr |
| Montana | $0–$35/yr |
| Wyoming | $60/yr |
| New Mexico | No report |
| Delaware | $400/yr |
| Nevada | $350/yr |
Ownership Transfer
Compare age, entity type and formation records against your goals.
We prepare the transfer documents for you to review and sign.
Timing depends on documents, payment and filings; foreign registration is separate.
Apply with the IRS to open accounts and apply for credit.
Use your updated documents and EIN to keep finances separate.
Open reporting vendor accounts and pay on time.
Colorado Specific
The state filings lenders check, and local places to bank, borrow and get free advice.
File the annual Periodic Report with the Colorado Secretary of State during your filing window. A delinquent entity is a common reason lenders and vendors pause an application.
Download a Certificate of Good Standing from the Secretary of State when a bank, lender or landlord asks for proof the company is active.
Keep the registered agent and principal office address on file current, and use the same address on IRS, bank and bureau records.
Register with the Colorado Department of Revenue through MyBizColorado if you sell taxable goods or have employees. Staying current supports a clean state record.
If you trade under a name other than the legal name, file a trade name with the Secretary of State so lenders can match the two.
We don't list Colorado-only vendors as “reporting” accounts: reporting policies change and are rarely published. Ask each supplier which bureau it reports to before you rely on the account.
Free, confidential advising on business plans, financing readiness and lender introductions, with centers across the state.
A Denver-based nonprofit lender (CDFI) that works with businesses that may not yet qualify for a traditional bank loan.
The state Office of Economic Development and International Trade lists state-supported financing and grant programs.
Lists SBA lenders, microlenders and events serving Colorado businesses.
Available Now
Compare package ages and request current verified inventory.
An entry-level option for entrepreneurs seeking an existing legal entity with a relatively recent formation history.
$1,700Package price
Request DetailsAn option for buyers who prefer a longer-established formation date when evaluating their business plans.
$2,950Package price
Request DetailsAn option for entrepreneurs seeking an older corporation or LLC with an extended legal formation history.
$3,950Package price
Request DetailsResources
D-U-N-S Number and PAYDEX score.
Commercial credit reports and Intelliscore Plus.
Commercial credit files and risk scores.
Apply for an Employer Identification Number free from the IRS.
Why CPNs and credit repair offers can be scams.
Search business records and filing history.
Common Questions
A baseline file can appear within 30–60 days of the first reporting accounts; a lender-ready profile commonly takes 6–18 months or more. These are ranges, not guarantees.
Some vendor accounts don't require one, but many cards and loans do. A mature business profile may reduce—not eliminate—reliance on guarantees.
No. An aged entity may help with time-in-business screens, but payment history still has to be built after transfer, and lenders review current owners and operations.
No. Most vendors don't report. Confirm with each supplier what it reports and to which bureau before you rely on it.
No. The FTC warns that using a CPN instead of your Social Security number on credit applications can be illegal.
80 or above generally indicates on-time or early payment; 1–49 indicates consistently late payment.
Request current Colorado shelf company inventory and transfer details. Educational information only—not legal, tax or financial advice; we are not a lender.
Add-On: Aged Domains
A domain registered 5+ years with real activity helps your company's online presence match its formation date during bank, vendor and lender reviews. It supports verification; it never guarantees approval.